All Categories
Featured
Final Expense and Burial Expense Planning
Table of Contents
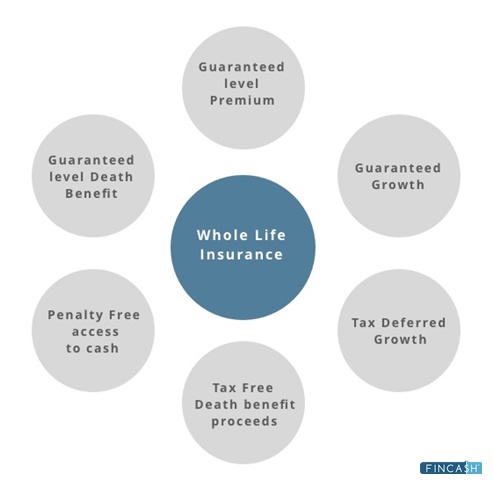
With whole life insurance, you get to decide how your dividends will be utilized. Here are a few of the options: Purchase additional insurance, which can increase your survivor benefit and built up money worth quicker than your policy's initial guarantees. When you utilize your dividend to purchase additional insurance, it sets a brand-new level of warranty from which the policy's values can't fall from one year to the next Minimize the quantity of premium you owe each year.
Your Northwestern Mutual monetary advisor can assist you figure out the best choice for you. Your policy will build up money value that's ensured to grow over time and isn't tied to the stock marketmeaning it will not decrease after a drop in stock rates.
When accessing your cash worth, you have a couple of options to think about. You can take a loan against your policy from the insurance provider. Payment of the loan is versatile, but interest will accumulate. If you pass away with a loan against the policy, your survivor benefit will be minimized by the quantity of the loan.
Best IUL Benefits for Retirement
This might be a good choice if you have a financial emergency situation or for larger, irregular needs, such as remodeling a home. When you surrender your policy, you'll no longer have your insurance. In lots of cases, when people need to access their cash value and no longer require their complete death benefit, they give up a part of their policy.
Medicare in EscondidoThis can likewise be useful from a tax viewpoint. That's because when you surrender a policy, you'll owe regular earnings tax on any cash worth above cash that you have actually paid in (or "basis"). In this case, you can take all the cash worth in your policy, but you likewise surrender all your life insurance coverage.
If you're thinking about tapping into your cash worth, your monetary consultant can help you think through the best choices for your situation. Throughout this time, your money value will continue to grow without you owing any money for your policy.
Affordable 2026 Term Life Insurance Rates Today
This benefit implies that modifications in your health won't impact your capability to get more insurance down the roadway.
, especially during down markets.
Otherwise, if you access those accounts while they are down, you 'd essentially be costing a loss.
1 Investopedia. How Whole Life Insurance Functions. Updated May 07, 2025. . Accessed March 26, 2026. Content within this post is offered general informational purposes and is not supplied as tax, legal, health, or financial guidance for any individual or for any particular scenario. Employers, staff members, and other people should call their own advisors about their circumstances.
Understanding Whole Life Insurance Functions
Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100.
B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. B61000, Juvenile series: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania, Texas & Virginia, Policies: ICC18B61JWO & ICC18B61JTO. In Delaware, Policies B61JWO & B61JTO. Q60000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania & Texas, Policy ICC18Q60200M.
In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID.

Latest Posts
Affordable Individual Health Insurance Rates in 2026
Essential Consumer Guide for Selecting 2026 Life Insurance
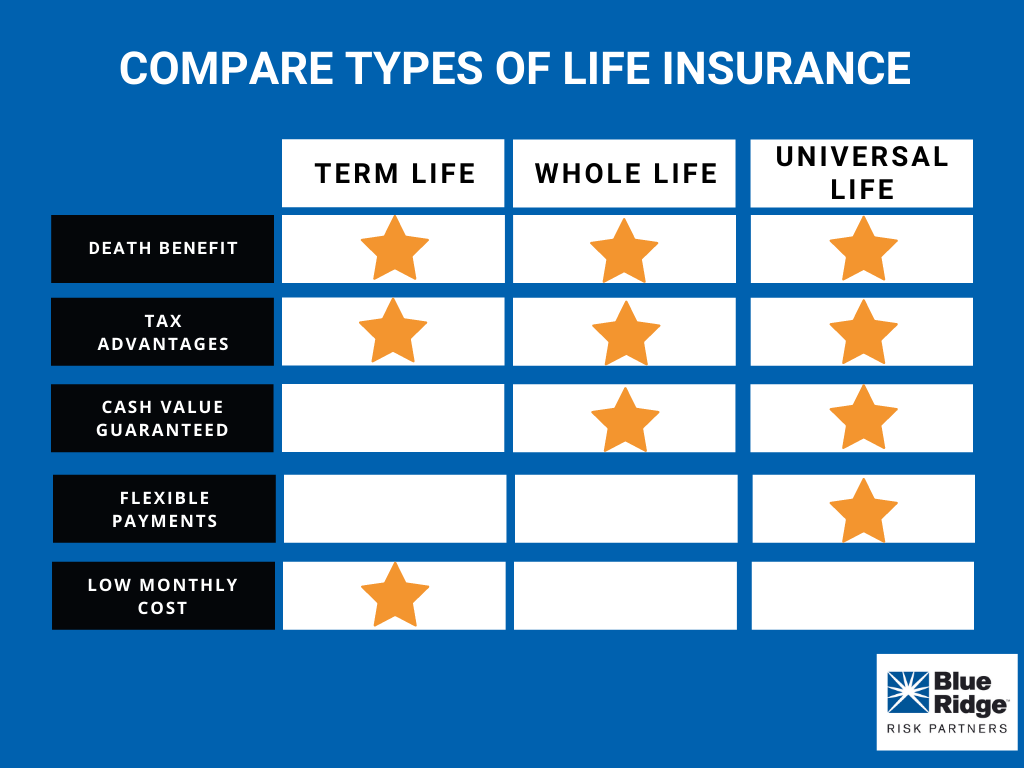
Reviewing Term and Whole Plans